Expert Insights

Tax, FDI, HR and legal updates — practical perspectives from the TrustlineAX team for businesses operating in Vietnam.

Receiving Export Payment Through an Intermediary Company in Vietnam: You Could Lose Your VAT Refund 01
VAT Refund

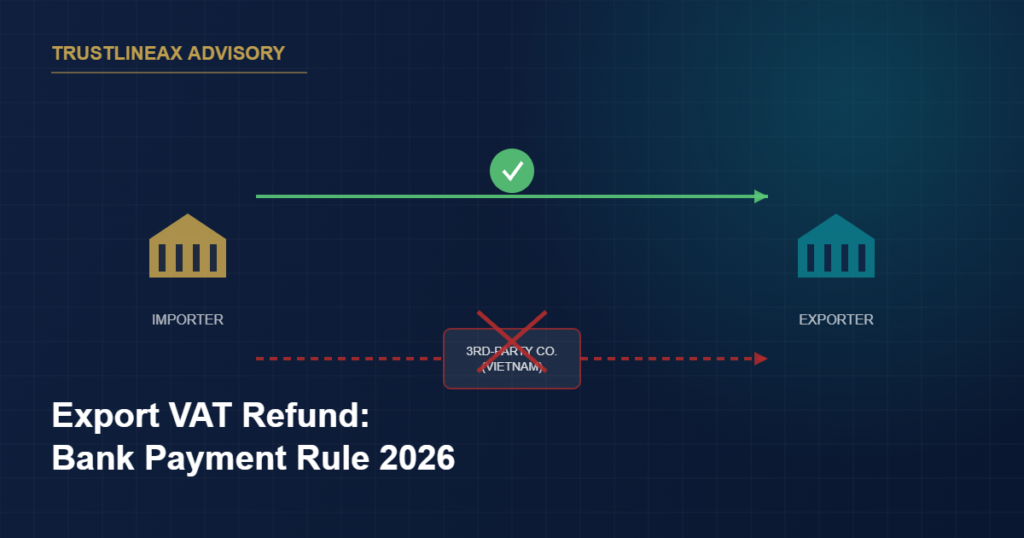
Receiving Export Payment Through an Intermediary Company in Vietnam: You Could Lose Your VAT Refund

The tax authority has issued an official letter restating the bank-payment condition for exported goods and services — if the exporter does not receive payment directly from the overseas importer but through another company in Vietnam, the input VAT may not qualify for deduction or refund. Trustlineax summarizes Official Letter No. 3251/CT-CS.
Buying Import-Origin Goods from a Local Trader Then On-the-Spot Exporting: Does Vietnam’s Ban on VAT Refunds for Import-Then-Export Still Catch You? 02
VAT Refund

Buying Import-Origin Goods from a Local Trader Then On-the-Spot Exporting: Does Vietnam’s Ban on VAT Refunds for Import-Then-Export Still Catch You?

An FDI supplier in the export processing supply chain had VND 58.2 billion in VAT refunds frozen for years under the rule that "imported goods subsequently exported are not eligible for a VAT refund" — even though it never imported the goods itself. The tax authority has now responded. Trustlineax summarizes Official Letter No. 5866/CT-CS.

Pay for Untaken Annual Leave on Termination: PIT-Exempt, or Still Subject to 10% Withholding? Official Letter 15676/DON-QLDN1 Explains 03
Personal Income Tax (PIT)

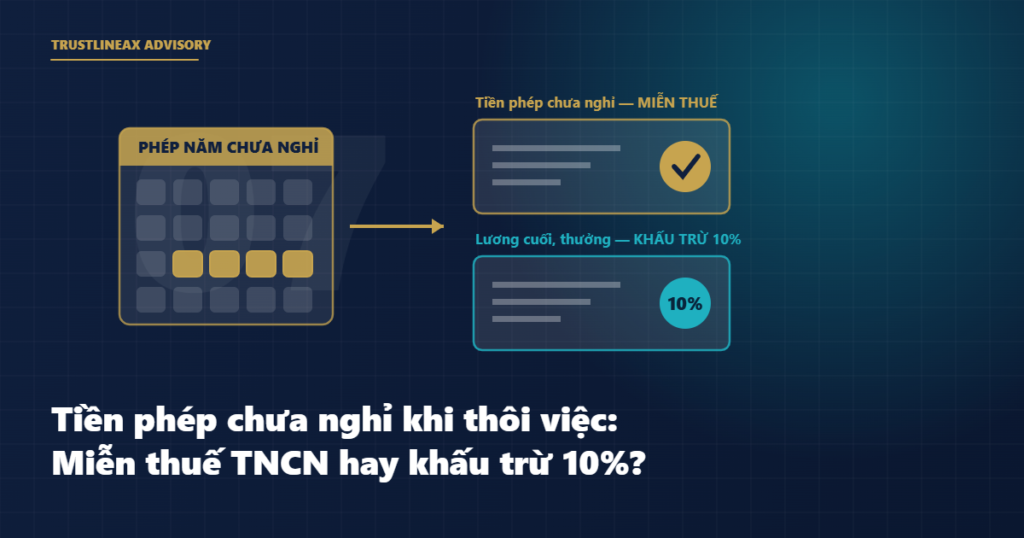
Pay for Untaken Annual Leave on Termination: PIT-Exempt, or Still Subject to 10% Withholding? Official Letter 15676/DON-QLDN1 Explains

An employee who leaves without using up their annual leave is paid for the untaken days — is that payment subject to personal income tax, and how does it differ from the 10% withholding on payments made after the labour contract ends? Trustlineax analyses Official Letter 15676/DON-QLDN1 (14 August 2026) from the Dong Nai City Tax Department and Decree 253/2026/ND-CP.

Gifts for Customers, Tet Gifts for Employees, Promotional Goods: From 1 July 2026, Businesses Can Issue ONE Consolidated Monthly/Quarterly Invoice Instead of a Separate Invoice for Each Transaction 04
Value Added Tax (VAT)

Gifts for Customers, Tet Gifts for Employees, Promotional Goods: From 1 July 2026, Businesses Can Issue ONE Consolidated Monthly/Quarterly Invoice Instead of a Separate Invoice for Each Transaction

From 1 July 2026, Decree 254/2026/ND-CP officially allows businesses to issue a CONSOLIDATED INVOICE on a monthly or quarterly basis for promotional goods/services and for goods/services given as gifts or donations — instead of issuing a separate invoice for each transaction as before. Trustlineax summarizes the conditions for applying this rule, what has changed from the previous regulation, and key points on the VAT taxable price.

Selling Shares or Capital Contributions in Vietnam? How Personal Income Tax on Capital Transfers Is Calculated Under the New 2026 Rules 05
Personal Income Tax (PIT)

Selling Shares or Capital Contributions in Vietnam? How Personal Income Tax on Capital Transfers Is Calculated Under the New 2026 Rules

Individual investors selling capital contributions or shares in a Vietnamese company must pay personal income tax on the transfer — but at what rate, and who is responsible for declaring and paying it? Trustlineax summarizes the rules under Personal Income Tax Law No. 109/2025/QH15, Decree No. 253/2026/ND-CP and Circular No. 89/2026/TT-BTC.

Withholding or Paying Tax on Behalf of Others in Vietnam Now Requires a Detailed Schedule: A New Rule from 1 July 2026 Many Businesses Have Missed 06
Tax Administration & Compliance

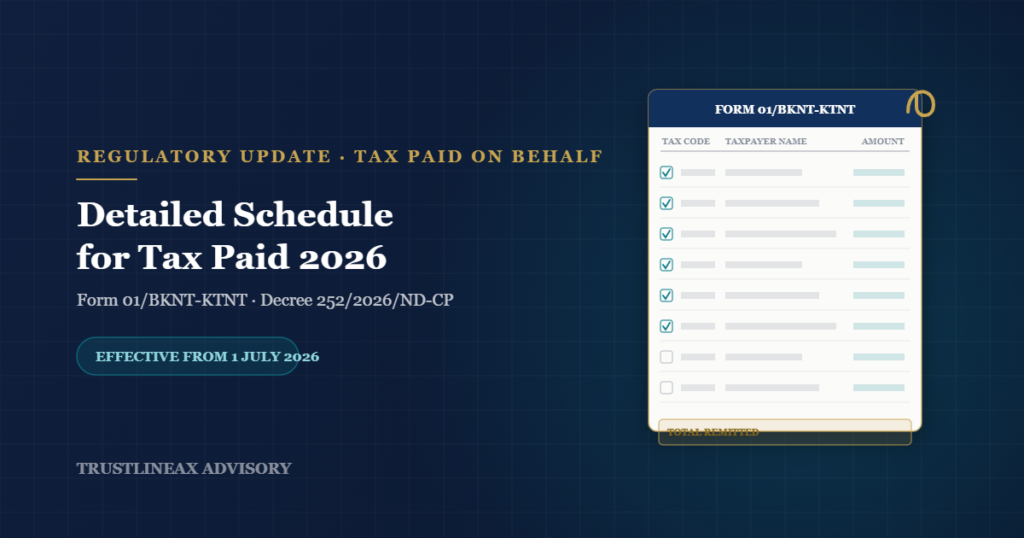
Withholding or Paying Tax on Behalf of Others in Vietnam Now Requires a Detailed Schedule: A New Rule from 1 July 2026 Many Businesses Have Missed

From 1 July 2026, organizations and individuals that withhold, declare, or pay tax on behalf of others in Vietnam must submit a detailed schedule of amounts paid (Form 01/BKNT-KTNT) together with the payment document — an entirely new requirement under Decree 252/2026/ND-CP and Circular 89/2026/TT-BTC.